Probate Recovery

More Data Won’t Fix a Broken Decision Process

Most Organizations Have a Decision Problem Rather Than a Data Problem

Over the past decade, data leaders built warehouses, licensed new feeds and launched dashboards across the enterprise. Yet the same accounts still stall in the same queues. More information arrived, but better decisions didn’t follow. The gap is whether your information is actionable data: verified, matched to the right record, owned by a specific person and tied to a defined next step. Without knowing what you’re looking at, even excellent data sits in a report until someone happens to notice it.

Why More Data Doesn’t Guarantee Better Decisions

Every new data source adds value. It also adds clutter, review time and reconciliation work. When teams can’t tell which inputs matter, they slow down or fall back on the old process. The cost for this can be substantial. Gartner research estimates that poor data quality costs organizations an average of $12.9 million per year. That figure counts bad data. It doesn’t count good data that never reached a decision.

That second cost has a name: decision latency, the time between a signal arriving and someone acting on it. Latency is where value quietly hemorrhages. Picture a lender that receives a monthly file of possibly deceased customers. The file lands in a shared folder. An analyst reviews it when time allows. By the time an account moves, the estate’s creditor claim window may have closed. The data was there. The decision process wasn’t.

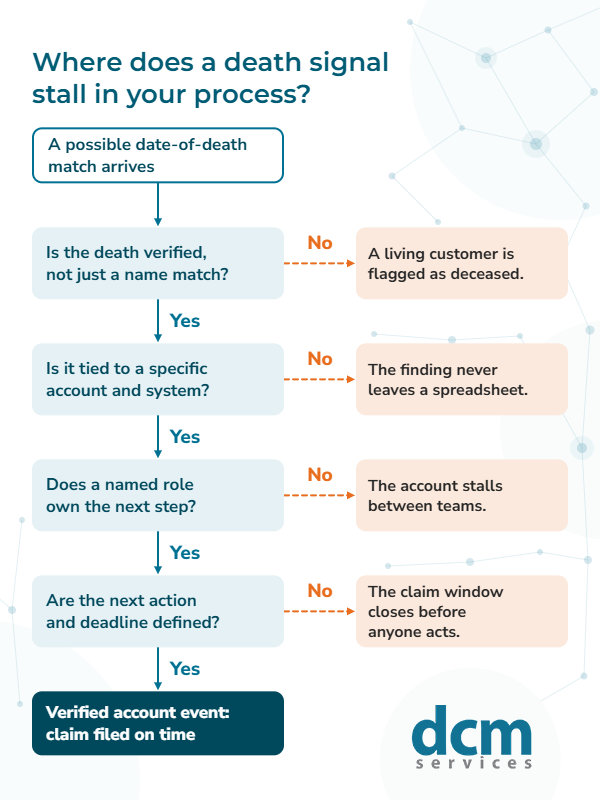
A Data Signal Is Not a Verified Account Event

Most data feeds deliver signals. Operations teams need events. The two are easy to confuse, and that confusion drives most downstream failures.

A data signal suggests something might be true. A name and date of birth resemble a death record. Mail comes back undeliverable. A phone number gets disconnected.

A verified account event confirms something is true, ties it to a specific account and carries enough context to act. A confirmed date of death, matched to the right account holder, with a known estate status, is an event.

Acting on unverified signals creates risk. A living customer flagged as deceased is a service failure and a potential compliance issue. Ignoring signals creates loss. Verification is what separates actionable data from the clutter. One source rarely gets you there, unless you have the tools and expertise we do at DCM Services.

The Four Requirements for Actionable Data

Actionable data meets four conditions. Miss one, and the chain breaks.

  1. Verified signal
    The information is confirmed against authoritative sources, not just matched on probability.

  2. Useful matching
    The event connects to the account, product and system where work actually happens, not just to a name in a file.

  3. Clear ownership
    A named team or role owns each event type. “Operations” is not an owner.

  4. Defined next action
    Each event triggers a documented step with a deadline: route the account, adjust contact, or file a claim.

Most organizations handle the first requirement well and assume the other three will follow. They usually don’t.

The four requirements that turn a data signal into a verified account event: verified signal, useful matching, clear ownership, and a defined next action.

How to Connect Research Outputs to Company Operations

Research outputs often end life as files. Files aren’t workflows. Actionable data needs a destination, and these five moves give it one:

  • Define the event
    Agree on what counts as confirmed and which fields every event must carry.

  • Route into the system of record
    Send events where work is assigned instead of an inbox or spreadsheet.

  • Attach a service level
    Give every event type a time-to-action target.

  • Measure outcomes
    Track accounts resolved rather than flagged records.

This is where transformation programs succeed or stall. The technology usually works. The handoff usually doesn’t.

Where Technology Meets Expertise

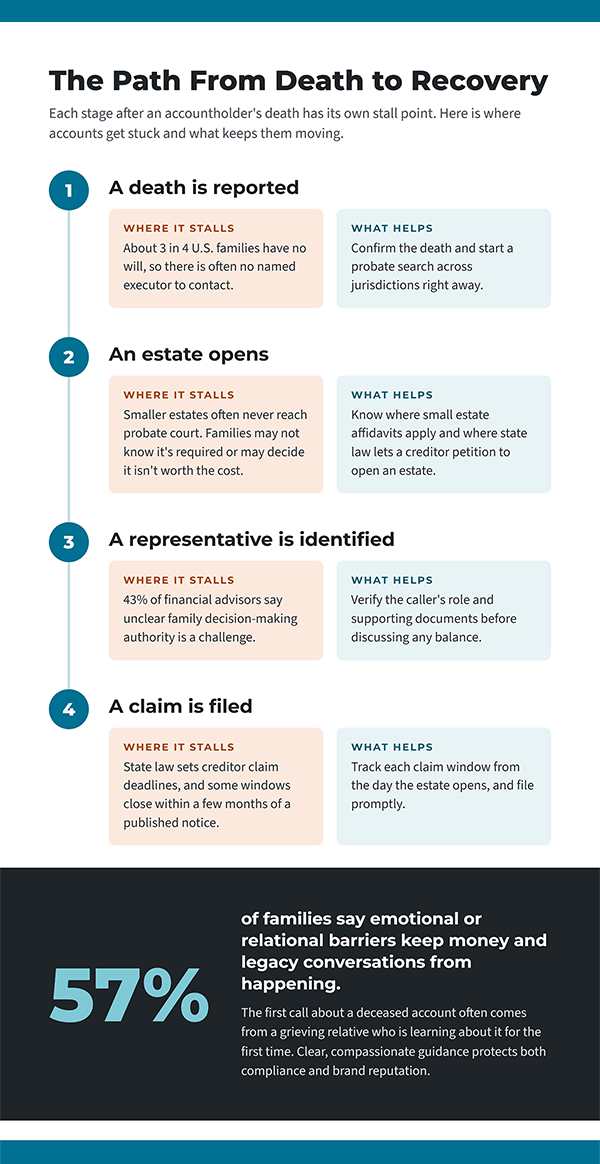
Deceased and probated accounts show the problem clearly. The data exists across thousands of courts and records. The hard part is turning it into the right action, on the right account, before the window closes.

Here at DCM Services, we pair proprietary probate research and patented date-of-death technology with specialists who translate findings into action. Our probate research covers more than 3,400 courts nationwide. Verified events then move into defined workflows: claims prepared and filed, accounts routed correctly and surviving families treated with respect. The goal isn’t necessarily to have more data. Rather, we care more about actionable data and fewer missed decisions.

Quick Answers

What is actionable data?
Actionable data is information that is verified, matched to a specific account or record, assigned to an owner and linked to a defined next step.

What is the difference between a data signal and a verified account event?
A data signal suggests something may be true. A verified account event confirms it, ties it to a specific account and provides enough context to trigger action.

Assess Your Data-to-Decision Readiness

Before you buy another data feed, test the ones you already have. The next time a date of death match lands on your desk, use "Data-to-Decision Readiness” to look from signal verification to defined next actions so you can see exactly where decisions stall. Whether you do this or not, feel free to contact us any time, and we’ll be delighted to go over your organization’s specific situation with you.

Decedent Account Recovery: The Gap Your Metrics Were Never Built To Show

Most problems in your collections operation announce themselves. You get a complaint. A service level slips. Numbers move the wrong way and someone wants an explanation by Monday. You get the idea.

Uncollected decedent balances announce nothing. They generate no exception report, no variance, no escalation. They sit in an inventory that was never assembled, and every report you run comes back clean. That silence is why this gap survives inside well-managed organizations. Over time, this is shaping up to be a serious issue. Baby Boomers (ages 62-80) have an average individual debt of over $92,000, according to Experian.

Clean Numbers Are Not Complete Numbers

Look at how your recovery performance gets calculated. Dollars recovered, divided by the accounts in your working inventory. Now look at what sits in that denominator: Accounts you identified. Accounts that triggered the collections process. Accounts someone got assigned. An estate that opened in a jurisdiction you never searched is not in there. A balance tied to a death your scrub failed to match is not in there. An account where no estate ever opened, but assets still exist, is not in there.

The painful truth is that your rate holds steady because the hardest accounts were never counted against it.

Then the incentive turns strange. Add those accounts to your inventory and your percentage can fall even as your dollars climb. Go looking for issues like this and the scoreboard penalizes you. Do nothing and you post another solid quarter. So where does that leave you?

The Question Has No Owner

These balances cross too many desks to belong to any individual. Servicing considers the account resolved. Finance considers the loss booked. Recovery works with what it receives. Compliance monitors how contact happens, not whether it happens at all. So the question "how much are we failing to find" belongs to nobody, and questions without owners do not get asked.

The accounting reinforces it. Once a balance is written off, the pain stops. Organizations respond to pain. This one quit hurting the day it was reserved. It’s not even considered what could be accomplished with a little proactivity and the right partner.

What You Gain By Asking Anyway

Almost every improvement you can champion requires money. New headcount, new platform, new budget cycle, new business case, new competition with three other priorities.

This one moves the opposite direction. These balances are already written down. Whatever comes back lands as margin. You are not asking anyone to fund a discovery.

The discovery itself stays small and reversible. Run a portion of your inventory against nationwide court records and see what surfaces. Maybe the answer is modest. That is still worth knowing, and it cost you a conversation. Maybe the answer is substantial, and you just delivered revenue that no forecast anticipated.

Use What You Find to Change What You Count

Your reporting rate starts with total dollars recovered. However, then you add a metric most organizations never track: identification coverage. What share of your deceased inventory did you actually locate, and how long did locating it take? Coverage exposes what rate conceals. An organization finding 40 percent of its decedent accounts and recovering aggressively on them has a very different future than one finding 90 percent. The rate can look identical. The dollars will not. Measuring the coverage can shine a light on the gap.

Help Closing the Gap

Running your current reports harder will not identify these gaps. They were built to measure the work you assigned, and this is work for which nobody was assigned. It surfaces when someone decides to ask “how much is out there unrecovered?” You are in a position to be that someone.

DCM Services helps organizations answer that question with nationwide court access and technology built specifically for decedent account recovery. Contact us and we will show you what your inventory actually holds.

Building a Specialty Account Strategy Reduces Delinquency and Maximizes Recovery Revenue

Every delinquent account looks the same sitting in a queue, but in reality, they aren’t the same and shouldn’t be treated as such. Some accounts belong to a borrower who missed a payment and will catch up on their own. Others belong to an estate, a bankruptcy trustee, or a family member who never expected to inherit a debt. Treating all of them the same way will create a situation where recovery slows while cost per account climbs.

See our recent article: The Hidden Cost of Treating Every Delinquent Account the Same: Why Specialty Collections Matter

A deliberate specialty account strategy does the opposite. It identifies these accounts early, routes them to the right process, and treats them as a distinct part of the portfolio instead of an exception. Done well, it's one of the more direct ways an organization can simultaneously reduce delinquency and maximize recovery revenue.

Understanding The Lifecycle of a Consumer Account

Most collections strategies are built around a predictable curve: current, early-stage delinquency, late-stage delinquency, charge-off, and post charge-off recovery. Segmentation by days past due, an escalating contact cadence, and settlement offers that grow more flexible as the account ages all assume the account will keep moving along that curve. The portfolio-level delinquency rate can obscure meaningful differences between borrower segments, though. The latest Federal Reserve analysis, for example, attributes much of the recent increase in credit-card delinquency to nonprime borrowers.

That predictable model works for a straightforward delinquency. However, it breaks down the moment a specialty condition enters the picture. A death, a bankruptcy filing, or active military deployment interrupts that standard curve. An account can look completely normal in a report and still be unrecoverable through standard channels, or recoverable only through a different one entirely.

Where Specialty Conditions Emerge

Specialty conditions rarely arrive with a flag attached.

  • A borrower may pass away and the account will sit untouched, potentially for months, before anyone notifies the servicer.

  • A bankruptcy petition triggers an automatic stay that ordinary collections activity can violate without anyone realizing it.

  • A cardholder enters active duty and gains protections under the Servicemembers Civil Relief Act.

  • A dispute changes what can legally be said, and to whom.

These conditions can surface at any point in the lifecycle: before charge-off, after charge-off, or even years into a placement with a third-party agency. The cost of missing one isn't limited to lost revenue. Continuing standard collections activity against an estate, a bankruptcy filing, or a protected servicemember creates real compliance issues, and potentially reputational exposure if collections efforts aren’t done with the compassion necessary to speak to familial estate executors.

Identifying the Right Intervention Point to Reduce Delinquency

Catching specialty conditions early is what actually moves delinquency numbers rather than waiting for a complaint or a returned letter which forces the issue. That means building detection into the process itself: routine scrubs against death records and probate filings, bankruptcy court data, and other public and licensed sources, rather than waiting for a condition to surface on its own.

Timing changes what's recoverable as well. A probate matter identified within weeks of a death can often be resolved through the estate's court-supervised process. The same matter identified months later may run into missed claims deadlines or a depleted estate. Late identification can close the door on recovering those balances completely.

Matching Account Characteristics to the Right Recovery Strategy

Not every specialty account calls for the same treatment, either. A probated estate with a named executor needs compliant, respectful communication with an authorized representative, not a standard collections script. A bankruptcy account needs proof-of-claim filing and case monitoring, not contact attempts. What matters is account type, portfolio size, and how much of the process an organization wants to manage in-house versus hand to a specialty partner.

That's why solutions in this space tend to fall into a few categories:

  • Self-service tools that let internal staff run their own research and keep recovery in-house

  • Full-service programs that manage resolution across probated and non-probated estates end to end

  • Dedicated servicing built around requirements like the bankruptcy lifecycle.

Matching the right category to the right account, instead of defaulting to one approach for everything, is what turns a specialty portfolio into a source of recovery revenue rather than a drag on it.

Balancing Automation with Human Judgment

Automation has clearly earned its place in specialty account work. Scanning probate filings and public records at scale, flagging date-of-death matches, and routing accounts by condition type are jobs technology handles faster and more consistently than a person can, assuming you have the right software. Our Probate Finder OnDemand® app, for example, is our in-house, proprietary automated solution.

Judgment still belongs to a person, however. Deciding how to approach a grieving family member, interpreting an ambiguous probate filing, or determining whether a bankruptcy discharge actually covers a specific account requires context no rules engine has. The organizations that get the best results treat automation as the intake and triage layer, and reserve trained staff for the parts of the process where tone, compliance judgment, and relationship handling decide the outcome.

Creating a Scalable Specialty Collections Program

A specialty account strategy only pays off if it can grow with the portfolio. That takes documented workflows for each specialty type, data sources that get refreshed on a schedule instead of checked once, and reporting that separates specialty recovery performance from standard delinquency metrics so the program's real return is visible.

It also takes a deliberate decision about what to build internally and what to source from a partner who already carries the licensing, the data relationships, and the compliance controls this work requires. Organizations across financial services, auto lending, mortgage servicing, and healthcare are all managing some volume of specialty accounts today. The ones treating it as a defined program, rather than an exception queue, are the ones seeing it reduce delinquency and maximize recovery revenue instead of quietly eroding both.

Ready to Build a Specialty Account Strategy?

Specialty accounts aren't going away. The only real question is whether they're identified early, routed correctly, and resolved by the right mix of technology and trained judgment, or left to work themselves out in a standard collections queue where they don't belong. If it's time to look at what a specialty account strategy could do for your portfolio, contact us to talk it through.

Probate Collections Start with Finding the Estate

For banks, credit unions, and consumer lenders, probate collections often begin too late.

When a borrower passes, the account does eventually get flagged. However, by the time someone checks whether an estate exists, where it was opened, who the estate executor(s) are, whether a claim can be filed, and what the applicable court requirements are, it’s usually after filing deadlines have passed and the account gets written off.

This sequence creates an avoidable problem: probate collections depend on timely estate identification, but many lenders still treat estate research as a “when we get to it” task. A more effective approach starts by making probate identification an integral part of the account lifecycle.

Probate Collections Require a Different Process

Traditional collections practices work because most accounts follow a relatively predictable path. Specialty accounts, including estates, bankruptcies, and conservatorships do not. These accounts can become subject to processes that vary not only by individual circumstance, but also by legal jurisdiction. The CFPB notes that a deceased person's debts are generally paid from the estate, while responsibility for managing those debts may fall to an executor, administrator, personal representative, or another authorized person under applicable law. 

That means a lender cannot simply transfer a deceased account to a conventional collections queue and expect the same process to work. The organization needs to answer different questions, such as:

  • Where was the estate opened?

  • Who is authorized to act for the estate?

  • Can we file a claim before the deadline?

  • What court requirements apply to this account?

  • How will we monitor the account during resolution?


Finding Probate Estates is Just The First Problem

For many lenders, especially credit unions managing thousands of member accounts, the practical challenge isn't knowing that probate exists, but rather finding the estate among a large portfolio of accounts.

Manual research can require staff to search court records, identify potential matches, verify estate information, and determine whether an account belongs to the estate. The work becomes more difficult when lenders operate across multiple jurisdictions.

That is why probate estate identification deserves its own place in the recovery strategy.

Our  Probate Finder OnDemand® service, for example, is designed specifically to automate probated estate location, matching, and claim presentation. The platform provides nationwide probate visibility and uses our proprietary Probate Finder technology to reduce reliance on manual, court-by-court research.

Why Credit Unions in Particular Should Pay Close Attention

Credit unions have another reason to examine this process closely: member relationships can make specialty-account handling especially sensitive. A credit union may want to preserve the member relationship with surviving family members while still fulfilling its responsibilities as a creditor. That requires a process that not only distinguishes the deceased borrower from the person authorized to manage the estate but does so with compassion and empathy.

Federal guidance reinforces the importance of that borrower vs. estate representative distinction. The CFPB explains that debt collectors may communicate about a deceased consumer's debt with people authorized to act for the estate, while they generally cannot treat family members as personally responsible for the deceased person's debt. 

For credit unions, that makes accurate estate identification more than a recovery exercise. It becomes part of a controlled process for determining who the organization should communicate with and how the account should move forward.

Finding the Estate Is Only the Beginning.

Once an estate is located, lenders still need to determine whether a claim is appropriate, prepare the necessary information, submit it through the applicable process, and monitor the account through resolution. Our probate technology works constantly to perform deceased-account identification, which results in our signature service being able to ensure quick estate location, thorough claim validation, timely filing, and ongoing monitoring. Learn more about these processes on our product page.

Build Probate Collections Into the Account Lifecycle

Between our probate recovery solutions, and Probate Finder OnDemand® for organizations that want to maintain aspects of recovery internally, we strive to be flexible for any size organization. A large bank may want an end-to-end outsourced solution, but credit unions and smaller lenders may want to retain control of internal collections operations while adding specialized probate research capabilities.

For organizations still treating probate research as an exception handled after someone notices a deceased account, we urge you to contact us and start a discussion around how we can potentially help your bottom line and at a substantial ROI.


 FAQ