Outsourcing for Specialty Collections: Why Complex Accounts Belong With Specialists

For years, outsourcing in financial services followed a simple strategy: move work to a lower-cost provider and save on staff. That equation still works for some functions, but for the most complex accounts in a portfolio, leaders now ask a different question: Which capabilities can we build well on our own, and which should we access through a partner?

Outsourcing for specialty collections sits at the center of that question. Deceased accounts, bankruptcy filings, and court-supervised cases make up a small share of most portfolios. They carry outsized regulatory, reputational, and financial weight. They also demand expertise, data, and technology that internal teams rarely get the chance to develop.

How Has Financial Services Outsourcing Evolved?

Outsourcing in financial services has moved through three broad stages. Most institutions still use a mix of all three.

Stage one: labor savings
Early outsourcing models focused on cost. Institutions moved call centers, data entry, and back-office tasks to providers with lower labor costs. Success meant a lower cost per account.

Stage two: capacity and performance
Collections teams added contingency placements and champion/challenger programs. Agencies competed on recovery rates. The institution placed accounts, measured results, and shifted volume to the top performer.

Stage three: capability access
Today, the strongest outsourcing relationships give institutions something they would struggle to build. That includes specialized expertise, proprietary technology, unique data, and compliance infrastructure designed for one type of account.

Each stage solved a real problem. The third stage matters most for specialty collections, because the work depends on depth that takes years to develop.

Why Do Specialty Collections Strain Internal Operations?

Most collections operations run on processes built for the common case. The account holder is known. The contact information is current. The next steps follow a predictable path. Policies, training, and technology all support that path.

Specialty accounts follow different rules, as outlined in our previous article, “The Hidden Cost of Treating Every Delinquent Account the Same: Why Specialty Collections Matter.” A deceased account requires estate research, probate filings, and conversations with grieving families. A bankruptcy account requires court filings, proof of claim deadlines, and strict adherence to the U.S. Bankruptcy Code. A court-supervised case requires coordination with a guardian, conservator, or other appointed party. Each one carries its own legal requirements, timelines, and documentation standards.

This creates what we call the economics of exceptions. It shows up in four ways.

  1. Low volume limits expertise
    When a team handles a few specialty accounts each month, staff rarely build deep pattern recognition. Procedures used once a quarter fade between cases. Training on them fades even faster.

  2. Knowledge concentrates in a few people
    Situations arise where a lone seasoned veteran often knows how to handle an unusual estate or a complex bankruptcy chapter. When that person retires or moves on, the knowledge leaves with them.

  3. Internal technology creates unseen gaps
    Internal IT teams prioritize systems that touch the most accounts. A tool that searches thousands of probate courts or tracks bankruptcy deadlines rarely wins that competition. Teams fill the gap with spreadsheets and manual research.

  4. Compliance depends on memory
    When specialty work runs on manual steps and individual knowledge, documentation thins out. Examiners and auditors often focus on exactly these files.

These pressures appear even in well-run operations. They also come from the math of low volume and high complexity.

Where Do Specialized Partners Create Advantage?

A specialized partner reverses the economics of exceptions. The accounts your team sees a few times a month make up a partner’s core workload. They handle that work every day, across many clients, and invest to match.

That focus creates advantages in five areas.

  1. Combined volume builds expertise
    A partner that works thousands of estate and bankruptcy cases sees patterns a single institution rarely encounters. Staff learn how different jurisdictions, chapters, and family situations play out.

  2. Technology and data spread across clients
    A partner can justify expensive tools that no single institution would fund alone. Examples include nationwide court monitoring and automated estate matching, such as our Probate Finder OnDemand® platform, and deceased and bankruptcy scrubs at scale.

  3. Trained staff handle sensitive conversations
    Specialty accounts often involve people going through a tough time. A surviving spouse or adult child may not know their rights or obligations and need a gentle, compassionate voice that effectively communicates these points. Representatives trained for these conversations protect the consumer and the institution’s brand.

  4. Compliance lives inside the workflow
    Specialists design each process around the rules that govern the account type. Deadlines, verification steps, and documentation become standard steps in every case.

  5. Reporting tracks outcomes
    A focused partner can show what happened to each account: when it was identified, which stage it reached, and how it resolved. That visibility supports performance management and exam readiness.

Which Functions Belong in Outsourcing for Specialty Collections?

Strong outsourcing decisions start with a clear view of what operations should stay internal. Core, high-volume work builds your institution’s skill and defines your customer relationships. Four tests help separate that core work from work that belongs with a specialist:

  1. Frequency
    How often does your team handle this type of account? High-frequency work builds internal skill on its own. Low-frequency work rarely does.

  2. Complexity
    How much does each case vary? Simple, repeatable tasks suit automation or a standard vendor. Work that changes by jurisdiction, bankruptcy chapter, or family situation calls for deep expertise.

  3. Consequence
    What happens when something goes wrong? Weigh regulatory exposure, reputational risk, and lost recoveries. A missed claim deadline can erase a recovery entirely. Some organizations face added stakes. Healthcare providers, for example, may need to document reasonable collection efforts on deceased patients’ accounts to support reimbursement claims.

  4. Cost to build
    What would it take to do this well internally? Count technology, data, training, and the time to reach full competence. Then compare that investment to the volume it would serve.

Plot each function on two dimensions: how often it occurs, and how complex and consequential it is. The matrix below shows where each combination usually belongs.
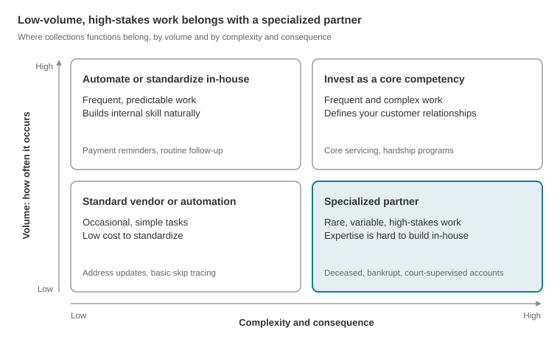
Where collections functions belong, and whether they should be handled internally or outsourced

Most specialty collections land in the lower-right quadrant, with low volumes, wide variations, and a high risk for serious consequences when handled poorly or non-compliantly. That combination makes these accounts strong candidates for a specialized partner.

Does Outsourcing Transfer Compliance Risk?

Outsourcing moves the work, but accountability stays with the institution. Federal banking regulators made this clear in their 2023 Interagency Guidance on Third-Party Relationships. Institutions must manage third-party risk across the full lifecycle: planning, due diligence, contract terms, ongoing monitoring, and termination. This raises the bar for partner selection. The right partner makes your oversight easier. Look for:

  • Audit-ready documentation on every account

  • Independent certifications such as SOC 2 Type 2 and ISO 27001

  • Clear complaint handling and escalation paths

  • Reporting that shows outcomes and exceptions at the account level

  • Proactive updates as laws and regulations change

The number of vendors matters too. Many institutions spread specialty accounts across several agencies. Each relationship requires its own due diligence, monitoring, and audits. Splitting low volumes across many vendors also keeps any single partner from building depth on your accounts.

Consolidating with fewer, more specialized partners reduces the oversight burden. It also gives each partner the volume to learn your portfolio inside and out.

What Role Do AI and Automation Play in Specialty Collections?

AI now appears on nearly every financial services roadmap. However, specialty collections present a particular challenge for these plans. AI performs best with large volumes of clean, relevant data. Inside any one institution, specialty accounts produce small data sets. A model trained on a few hundred deceased or bankrupt accounts a year has little to learn from. It also has few examples of the edge cases that matter most.

Specialized partners hold an advantage here. They work with far larger data sets for each account type. They know which steps follow clear rules and which require judgment. That knowledge lets them apply automation where it adds the most value:

  • Matching accounts to estate records and court filings

  • Flagging new bankruptcy filings and deceased indicators

  • Tracking claim deadlines across jurisdictions

  • Routing each account to the right workflow from day one

The best results pair automation with well-trained people. Technology handles identification, matching, and tracking at scale. People handle conversations with families, claim review, and decisions that require context. This balance improves speed and accuracy while keeping every consumer interaction human.

When you evaluate partners, ask how they use AI and automation. What data trains their models? How do they test for accuracy? Where do humans remain involved? Additionally, evaluate their understanding of these models. Did the agency build proprietary processes with efficacy and compliance in mind, or did they simply piecemeal together a working model from several technology vendors without fully understanding how they operate? From a cost perspective, remember there is overhead associated with purchasing these models that gets passed to their clients. Finally, from the regulatory aspect of interagency guidance, always consider the fact a partner’s technology becomes part of your risk profile. These issues deserve the same scrutiny as any other part of your due diligence during the partner selection process.

What Should Leaders Look for in a Specialty Collections Partner?

A partner’s focus, history, and reporting reveal more than any sales presentation. Use these questions to guide your evaluation:

  • Focus
    How much of the partner’s business centers on specialty accounts? Depth comes from repetition.

  • Experience
    How long has the partner worked these account types? How tenured are its managers and agents?

  • Proprietary technology and data
    What can the partner do that your team would struggle to replicate?

  • Compliance and security
    Which certifications do they hold? How do they document each step of each account?

  • Consumer experience
    How do they train staff for sensitive conversations? What support does it offer surviving family members?

  • Reporting
    Does the partner report on outcomes and exceptions at the account level?

  • Partnership model
    Will they consult on strategy, process design, and regulatory change?

How Should Your Operating Model Change?

Outsourcing for specialty collections works best as part of a deliberate operating model. The first step is drawing a clear line between strategy and execution. Your team keeps ownership of risk appetite, policy, performance targets, and third-party oversight. The partner owns the day-to-day work: identification, research, filings, communication, and resolution, all within standards you agree on together.

Shared measures keep both sides focused on results. Outcome-based KPIs work best, such as track recovery rates, time to resolution, claim filing timeliness, complaint rates, and how well exceptions get handled. These measures show whether accounts actually reach resolution.

Data and communication work to hold the model together. Secure, regular data exchange gets accounts to the partner quickly and brings results back cleanly. Expediency matters, because many specialty processes run on fixed deadlines. Regular meetings give both teams a chance to review results, discuss regulatory changes, and adjust processes together. The strongest relationships work like an extension of your team.

This structure lets each side do what it does best. Your team keeps control of strategy and risk. Your partner brings the depth that specialty accounts demand.

The Question Every Leadership Team Should Ask

Start with one question: If we built a specialty collections operation from scratch today, what functions would we choose to build ourselves, and what are the challenges?

For specialty accounts, most institutions reach the same answers.

  • “The expertise takes years to develop.”

  • “The technology serves too few accounts to justify internally.”

  • “The compliance stakes keep rising as the population ages and more accounts move into estates.”

All of these point to allowing a strategic partner to create a mutually beneficial relationship. Your team can focus on the work that defines your institution, and the partner handles the accounts that demand its depth. The result for you is stronger recoveries, cleaner compliance, and a better experience for the families and consumers behind every account.

Want to see how specialty accounts fit into your operating model? Contact us to review your current approach and talk through where a specialized partner can help!


Frequently Asked Questions about Specialty Collections Partners

More Data Won’t Fix a Broken Decision Process

Most Organizations Have a Decision Problem Rather Than a Data Problem

Over the past decade, data leaders built warehouses, licensed new feeds and launched dashboards across the enterprise. Yet the same accounts still stall in the same queues. More information arrived, but better decisions didn’t follow. The gap is whether your information is actionable data: verified, matched to the right record, owned by a specific person and tied to a defined next step. Without knowing what you’re looking at, even excellent data sits in a report until someone happens to notice it.

Why More Data Doesn’t Guarantee Better Decisions

Every new data source adds value. It also adds clutter, review time and reconciliation work. When teams can’t tell which inputs matter, they slow down or fall back on the old process. The cost for this can be substantial. Gartner research estimates that poor data quality costs organizations an average of $12.9 million per year. That figure counts bad data. It doesn’t count good data that never reached a decision.

That second cost has a name: decision latency, the time between a signal arriving and someone acting on it. Latency is where value quietly hemorrhages. Picture a lender that receives a monthly file of possibly deceased customers. The file lands in a shared folder. An analyst reviews it when time allows. By the time an account moves, the estate’s creditor claim window may have closed. The data was there. The decision process wasn’t.

A Data Signal Is Not a Verified Account Event

Most data feeds deliver signals. Operations teams need events. The two are easy to confuse, and that confusion drives most downstream failures.

A data signal suggests something might be true. A name and date of birth resemble a death record. Mail comes back undeliverable. A phone number gets disconnected.

A verified account event confirms something is true, ties it to a specific account and carries enough context to act. A confirmed date of death, matched to the right account holder, with a known estate status, is an event.

Acting on unverified signals creates risk. A living customer flagged as deceased is a service failure and a potential compliance issue. Ignoring signals creates loss. Verification is what separates actionable data from the clutter. One source rarely gets you there, unless you have the tools and expertise we do at DCM Services.

The Four Requirements for Actionable Data

Actionable data meets four conditions. Miss one, and the chain breaks.

  1. Verified signal
    The information is confirmed against authoritative sources, not just matched on probability.

  2. Useful matching
    The event connects to the account, product and system where work actually happens, not just to a name in a file.

  3. Clear ownership
    A named team or role owns each event type. “Operations” is not an owner.

  4. Defined next action
    Each event triggers a documented step with a deadline: route the account, adjust contact, or file a claim.

Most organizations handle the first requirement well and assume the other three will follow. They usually don’t.

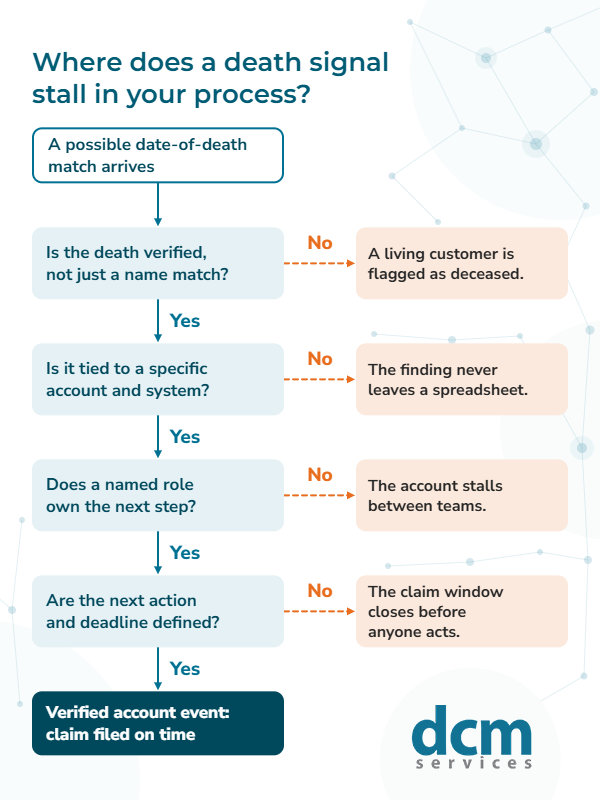
The four requirements that turn a data signal into a verified account event: verified signal, useful matching, clear ownership, and a defined next action.

How to Connect Research Outputs to Company Operations

Research outputs often end life as files. Files aren’t workflows. Actionable data needs a destination, and these five moves give it one:

  • Define the event
    Agree on what counts as confirmed and which fields every event must carry.

  • Route into the system of record
    Send events where work is assigned instead of an inbox or spreadsheet.

  • Attach a service level
    Give every event type a time-to-action target.

  • Measure outcomes
    Track accounts resolved rather than flagged records.

This is where transformation programs succeed or stall. The technology usually works. The handoff usually doesn’t.

Where Technology Meets Expertise

Deceased and probated accounts show the problem clearly. The data exists across thousands of courts and records. The hard part is turning it into the right action, on the right account, before the window closes.

Here at DCM Services, we pair proprietary probate research and patented date-of-death technology with specialists who translate findings into action. Our probate research covers more than 3,400 courts nationwide. Verified events then move into defined workflows: claims prepared and filed, accounts routed correctly and surviving families treated with respect. The goal isn’t necessarily to have more data. Rather, we care more about actionable data and fewer missed decisions.

Quick Answers

What is actionable data?
Actionable data is information that is verified, matched to a specific account or record, assigned to an owner and linked to a defined next step.

What is the difference between a data signal and a verified account event?
A data signal suggests something may be true. A verified account event confirms it, ties it to a specific account and provides enough context to trigger action.

Assess Your Data-to-Decision Readiness

Before you buy another data feed, test the ones you already have. The next time a date of death match lands on your desk, use "Data-to-Decision Readiness” to look from signal verification to defined next actions so you can see exactly where decisions stall. Whether you do this or not, feel free to contact us any time, and we’ll be delighted to go over your organization’s specific situation with you.

Compliant Collections Processes Can Still Fail in Practice

Compliant collections processes can look solid on paper. There's a policy, a training module, and a sign-off log proving every relevant person reviewed it. The problem with that is a policy only states what should happen. It says nothing about what happens once an account stops behaving like a typical case. That gap creates real risk, and it rarely surfaces until an examiner, a court, or a frustrated customer finds it first.

What a Compliant Collections Process Requires

Most accounts move through a workflow built for the common case where details like the account holder and contact information is known. The next steps are predictable, and teams write policies for that common case. Audits then check two things: does the policy exist, and did staff complete training. Audits rarely test whether the process survives an account that breaks the pattern. That blind spot sits at the center of most compliance failures.

Specialty accounts expose that gap fastest. For example, an account holder passes away, which results in a balance in a bankruptcy filing, where a court or probate process takes over the case. Each of these demands its own steps: identify the right representative, verify legal status, follow court timelines. A truly compliant collections process plans for these cases in advance. Skip that planning, and someone improvises, which is terrible for compliance. Improvisation is hard to document, audit, or defend later.

Where Compliant Collections Processes Break Down

Look past the policy document, and three patterns repeat:

  • Memory routes exceptions, not rules
    A veteran collector remembers which accounts need a different path. That knowledge lives with the person, not the system. When they leave, the account erroneously reverts to the standard path.

  • Teams blur ownership at the handoff
    An unusual account often sits between teams. Collections assumes legal owns it. Legal assumes servicing still does. No one owns the resolution, so nothing moves.

  • Documentation thins out where it matters most
    A routine file stays complete. A complicated file often has the biggest gaps, and is the most likely one an examiner will pull.

  • Reporting shows activity, not outcome
    Dashboards track calls made and letters sent. Few track whether a flagged account actually reached resolution. A compliant collections process should report on outcomes, not just activity.

None of this means the policy is wrong. It simply means no one tested it against the hardest cases.

How to Test a Compliant Collections Process

Stop asking whether a policy exists and start asking whether you can prove it. Can you show, case by case, how a complex account moved while also having it correctly flagged, routed to the right team, and closed on a documented timeline? Can you prove that without leaning on one person's memory?

For organizations managing deceased, bankrupt, or court-supervised accounts, this isn't a hypothetical question. These accounts need a structured workflow of their own rather than an exception bolted onto a system built for something else. That means automated identification, so accounts never sit unflagged. It means a documented process from the moment a case surfaces through resolution. It means reporting that shows an examiner exactly what happened and when, not what should have happened.

The strongest compliance programs don't rely on the thickest policy manual. They rely on collections processes that hold up the moment someone actually checks.

If any of this resonates with you and your team when discussing your organization’s collections processes, contact us so we can take a look at your processes and potentially identify any gaps.


The Federal Trade Commission's debt collection guidance offers a useful resource for understanding key consumer protection requirements and the standards that govern debt collection.

The Borrower Lifecycle Continues When Account Holders Pass Away

Financial services leaders should treat these instances as a predictable part of portfolio management rather than an exception

Financial services organizations have become incredibly sophisticated at almost every stage of the customer lifecycle. Between investing heavily in acquiring customers, underwriting them, servicing their accounts, identifying risk, managing delinquencies, and recovering losses, it's a complex, but well-oiled machine.

But there is one part of the lifecycle that doesn't always receive the same strategic attention: “What happens when a customer passes away?”

While that may sound like a narrow operational question, it's actually a much broader leadership question. Simply put, customers will inevitably pass away. It is a natural part of life. And while the customer relationship changes, the financial obligations and administrative responsibilities associated with an account don't simply disappear. This is a predictable part of managing a consumer portfolio. So, with that in mind, why do we still treat these accounts like exceptions?

Complexity isn't a good reason to accept a poor process

One explanation is that resolving accounts following a customer's passing can be complicated, and that's a fair point. An organization may need to determine when the customer passed away, whether an estate has been established, who is authorized to represent that estate, whether a claim can be filed, what deadlines apply, which jurisdiction rules govern the process, and more.

The regulatory framework recognizes that this is different from ordinary collections. For example, Regulation F treats an executor, administrator, or personal representative of an estate as the person who can act on behalf of the estate in relevant debt-collection communications, according to the Consumer Financial Protection Bureau. There is a lot to get right, but Complexity motivates us to understand the process better and is not a reason to stop improving.

When something is difficult, the natural organizational response is often to push it into an exception queue:

  • "Someone else will handle it."

  • "We'll review it when it becomes delinquent."

  • "We'll research it manually."

  • "We'll deal with it when we have time."

Eventually, some of those accounts become write-offs because a reactive process never identified them or attempted to collect on them in time. That's an important distinction, and it's also the underlying problem.

Estate accounts aren't simply a collections issue

It’s arguably a mistake to view accounts following a customer's passing strictly through the lens of collections. While there is certainly a financial component, legitimate obligations don't disappear simply because a customer has passed away. The process also involves data, technology, compliance, operations, and the customer experience.

Most importantly, it involves people who may be navigating one of the most difficult periods of their lives. The goal should never be to treat a grieving family member like an ordinary delinquent customer. The goal is to identify the right party, understand the estate, follow the applicable requirements, and resolve the account correctly. That distinction is crucial with estate accounts. It is possible to protect the financial interests of an organization while treating surviving family members and estate representatives with respect. We do it every day at DCM Services; performance and compassion are both measures of whether we've designed the process correctly.

Technology should help us see what we can't see manually

Today’s technology can make a meaningful difference with artificial intelligence and automation. Much of it focuses on replacing manual tasks or reducing headcount. There is another, sometimes more valuable, application of technology revolving around the discovery of important work opportunities that humans would otherwise never see.

Consider a traditional estate-recovery process. An organization may know that some of its customers have passed away. But knowing that isn't enough. The organization needs to identify the relevant estate, determine whether recovery is appropriate, understand where that estate is in the process, and act within applicable timeframes.

That can become extremely difficult to do by hand, much less scale. Technology can change the equation by making identification more systematic. At DCM Services, for example, our technology is designed to automate date-of-passing verification and identify probated estates using a nationwide probate database. That allows organizations to move from manually searching for opportunities to systematically identifying them.

But technology alone isn't the answer. A bad process automated is still a bad process. The real opportunity comes from combining technology with specialized expertise, tight project management, compliance controls, and training employees to understand how to handle these situations with care.

A 7,500% lesson in operational thinking

We at DCM Services recently saw a particularly striking example of what can happen when an organization changes the way it approaches this problem.

A mid-size credit union client using DCM Service's Probate Finder OnDemand® technology generated $1.86 million in probate claims during its first year and reported a 7,500% return on their investment. One partial month of settlements was enough to cover a full year of the service. Those are impressive numbers, but the most interesting part isn't the results themselves, rather the ideas, processes, and technology that made the numbers possible. Read the full case study here.

Every organization has processes that have become so familiar that people stop questioning them. Everyone knows they're manual and inefficient. Everyone knows there are probably missed opportunities. But because the process has always worked well enough, it doesn't make its way to the top of the executive agenda. That is, until someone changes the process and discovers how much value was sitting behind it.

The executive questions financial services organizations should be asking

Not every financial institution needs to build the same estate-recovery operation, but but every organization managing consumer accounts should understand what happens when their account holder passes away.

And that starts with asking some basic questions:

  • "How quickly do we know when a customer passes away?"

  • "What happens to that account after we know?"

  • "Who owns the process?"

  • "How do we determine whether an estate exists?"

  • "How do we identify the right representative?"

  • "How do we make sure we're acting within the applicable requirements and deadlines?"

  • "How much recoverable value are we currently writing off because our process doesn't identify it in time?"

Working through these questions will likely surface gaps in your organization's workflows and technology. That's often the stage we find clients in when they first reach out to us.

A more complete view of the customer lifecycle

The front end of the customer lifecycle has become increasingly sophisticated over the last few decades, understandably. But there is still a process to manage, value to protect, and compliance requirements to meet. And of course, there are still grieving people on the other side of the process who deserve to be treated with dignity and respect. Organizations that approach these accounts with that mindset will be better positioned to manage risk, protect revenue, and deliver a more thoughtful experience. How an organization handles the difficult and sensitive moments in a customer relationship often tells you how mature its overall operation really is.

So the next time your leadership team reviews the customer lifecycle, add one question to the agenda:

"What happens when one of our customers passes away?"

If the answer is complicated, that's okay. Complexity isn't the problem. The question is whether you're willing to build a better way to manage it, with the right balance of technology, expertise, performance, and compassion. If so, contact us today and we’ll get you what you need to significantly boost your estate collections revenue!